How Much Does a 15 Minute Primary Care Appointment Cost?
A 15 minute primary care visit can cost $0 to $250 or more. See what drives the bill, what is billed separately, and how to avoid surprise charges.
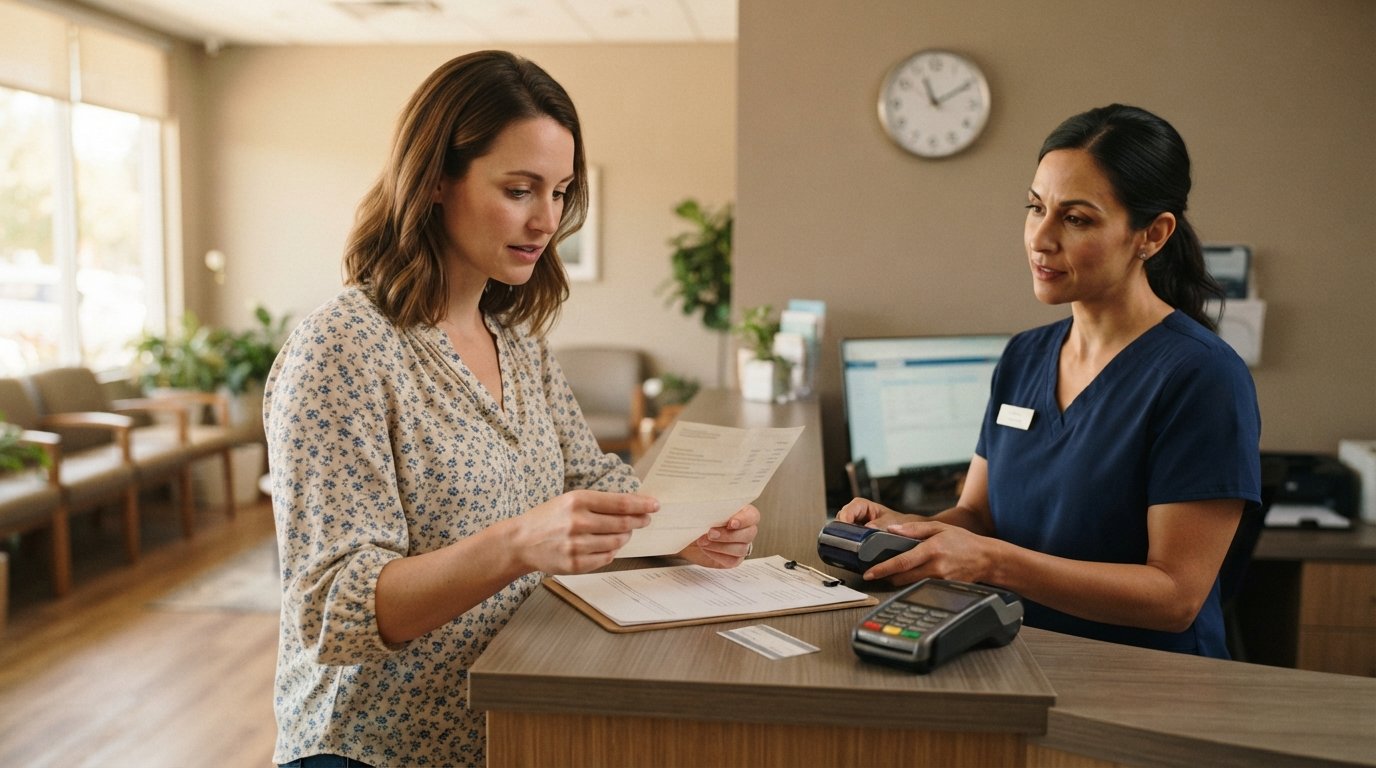
A 15 minute primary care appointment can cost anywhere from $0 to more than $250, depending on your insurance, location, and what happens during the visit. That is a wide range, and it is the reason so many people end up confused by a bill that arrives weeks later. The price you see quoted online, the amount your insurer allows, and the final amount you owe are rarely the same number. Understanding how a short visit is priced helps you ask better questions before you book, compare cash-pay rates honestly, and avoid surprise charges that have nothing to do with how long the clinician spent with you.
This guide breaks down the real cost drivers behind a brief primary care visit. It covers how visit length and complexity affect the bill, what is bundled into the office fee versus billed separately, how insurance copays compare with cash-pay rates, and why a 15 minute slot may not be enough for certain symptoms. The goal is practical: help you predict the cost of a short visit and recognize when the appointment length itself is working against you.
What Drives the Cost of a 15 Minute Primary Care Appointment
The billed cost of a short primary care visit is not set by the clock alone. Clinicians and billing departments use evaluation and management codes, often called E/M codes, to describe the level of work involved. A 15 minute appointment that addresses one simple problem, such as a mild rash or a medication refill, usually maps to a lower-level code. A 15 minute appointment that turns out to involve two chronic conditions, a new symptom, and a review of labs maps to a higher-level code even though the scheduled slot was short. That is the first surprise many patients encounter: the visit length is a scheduling convenience, not a guaranteed price.
Location is the second major driver. Primary care prices vary widely by geography because overhead, clinician wages, and local market competition differ. A brief visit in a rural clinic, a suburban group practice, and a downtown academic center can carry very different billed charges for the same 15 minutes. Site of service matters too. A visit inside a hospital-owned clinic often carries a facility fee on top of the professional fee, which can push the total cost of a short appointment significantly higher than the same visit in a freestanding office.
Insurance status changes what you actually pay, but not what is billed. The billed charge is the starting number. The allowed amount is what your insurer has negotiated. Your cost sharing, whether a copay, coinsurance, or deductible, is calculated from the allowed amount. For a 15 minute primary care appointment, the billed charge might be $150, the allowed amount might be $95, and your copay might be $25. If you are uninsured or using a cash-pay rate, you may be quoted something closer to the allowed amount or a discounted self-pay price. The same 15 minutes can feel free, cheap, or expensive depending on which of these numbers applies to you.
What Is Bundled Into the Visit Fee and What Is Billed Separately
A primary care visit fee is not an all-inclusive package. The office fee typically covers the clinician's time, the room, basic supplies, and the documentation that goes with the encounter. It usually does not cover lab work, imaging, procedures, vaccines, or after-hours communication that turns into a separate encounter. That distinction matters enormously for a short visit, because a 15 minute appointment that includes a rapid strep test, a urine dipstick, or a wart removal will generate charges beyond the visit fee itself.
Labs are the most common source of unexpected cost after a brief primary care appointment. A clinician may order a complete blood count, a metabolic panel, a thyroid test, or a point-of-care test during the visit. Each test has its own price, and the price depends on where the sample is processed. A test run in the office may be billed as a lab service, while a test sent to an outside reference lab may be billed separately by that lab. Patients often receive two bills: one from the clinician's office and one from the laboratory. The 15 minute visit fee does not absorb those costs.
Procedures and supplies follow the same logic. An ear irrigation, a joint injection, a skin biopsy, or a splint may be billed in addition to the visit. Even some seemingly minor items, such as certain medications administered in the office, can appear as separate charges. If you want to predict the total cost of a short appointment, ask two questions before the visit: what does the visit fee include, and what common add-ons are billed separately? The answers vary by practice, but a good front desk or billing office can usually explain the pattern.
- Typically included in the visit fee: clinician time, basic exam, routine documentation, simple in-office screening that is part of the encounter.
- Typically billed separately: laboratory tests, imaging, procedures, vaccines, durable medical equipment, and some in-office medications.
- Sometimes billed separately: after-hours phone or portal care that meets the criteria for a separate service, and forms or letters that require significant clinician time.
That list is a general guide, not a universal rule. Some practices bundle more generously than others, and some insurers require separate billing for services that another plan would include. The practical takeaway is that a 15 minute visit is a starting point for cost, not a ceiling. If your appointment involves testing or a procedure, plan for additional charges and ask for the self-pay price of each add-on if you are paying cash.
Insurance Copays vs Cash-Pay Rates for a Brief Visit
Insurance and cash pay are two different pricing worlds, and the gap between them for a 15 minute primary care appointment can be large. With insurance, your out-of-pocket cost is usually a copay or coinsurance applied to a negotiated rate. A typical primary care copay might fall in the $0 to $50 range for many commercial plans, though high-deductible plans can require you to pay the full allowed amount until the deductible is met. In that case, a short visit that would cost a $25 copay on a traditional plan could cost $100 or more on a high-deductible plan, because the negotiated rate applies to your deductible rather than a flat copay.
Cash-pay rates are the prices a practice charges patients who are not using insurance. These rates are often lower than the billed charge but higher than a typical copay. A brief visit at a direct primary care practice might be covered by a monthly membership fee rather than a per-visit charge, which changes the math entirely. A retail clinic or urgent care may post a flat cash price for a short visit, sometimes in the $75 to $150 range, while a traditional primary care office may quote a self-pay rate closer to its allowed insurance amount. The key is to ask specifically for the self-pay price of a 15 minute visit and to confirm what that price includes.
There is also a middle path: some patients use a health savings account or a transparent cash-pay arrangement for a brief visit because the total cost is predictable and lower than their deductible-adjusted insurance price. That can work well for simple, low-complexity concerns. It works less well when the visit is likely to generate labs or follow-up, because the cash price for the visit does not cover those extras. Before choosing cash pay, ask whether the quoted rate includes any point-of-care testing and whether the practice offers a bundled price for common short visits.
Why a 15 Minute Visit May Not Be Enough for Certain Symptoms
A 15 minute slot is a reasonable fit for a focused problem: a medication refill, a mild skin complaint, a simple respiratory infection, or a quick follow-up on a stable condition. It is a poor fit for anything that requires a full history, a careful review of multiple symptoms, or shared decision-making about a new diagnosis. When a short visit is used for a complex concern, the appointment may end with incomplete answers, a request to come back, or a referral, and the follow-up visit adds cost and time. In that sense, the cheapest-looking appointment can become the most expensive path if it does not resolve the question.
Several situations commonly need more than 15 minutes. New or worsening chest pain, shortness of breath, unexplained weight loss, persistent fatigue, and neurological symptoms all require a more thorough evaluation. Multiple chronic conditions that need medication adjustments, a new mental health concern that requires screening and discussion, and any visit that involves several preventive services are also poor candidates for a brief slot. In these cases, the visit length is not just a scheduling detail; it affects the quality of the assessment and the likelihood that you leave with a clear plan.
Telehealth adds a useful layer to this conversation. A short virtual visit can be an efficient way to handle a narrow question, review a lab result, or discuss a refill, and it often costs less than an in-person visit because there is no facility fee and no commute. But a virtual visit has the same complexity limits as an in-person one. If your symptoms need a physical exam, imaging, or labs, a 15 minute video appointment may end with a recommendation to seek in-person care. That is not a failure of telehealth; it is a sign that the appointment length and modality should match the problem. Educational resources, including the treatment explainers published on DoctorsHome, can help you understand what a short visit can realistically cover and which questions are better suited to a longer appointment.
How to Predict and Control the Cost of a Short Primary Care Visit
The most reliable way to control cost is to ask specific questions before the appointment. Start with the visit fee and what it includes, then ask about the most likely add-ons for your concern. If you have insurance, confirm whether the visit will be billed as preventive or problem-oriented, because preventive visits are often covered at no cost while problem-oriented visits may trigger cost sharing. If you are paying cash, ask for the self-pay rate in writing and confirm whether point-of-care tests are included. These questions take a few minutes and can prevent a much larger surprise later.
It also helps to match the appointment type to the problem. A single, straightforward concern is a good fit for a 15 minute visit. A new or complex concern deserves a longer slot or a visit type designed for it. If you are unsure, describe your symptoms when you book and ask whether the scheduler recommends a longer appointment. Front desk staff often know which concerns routinely need more time, and they can steer you toward the right slot. That simple step reduces the chance of a rushed visit that ends in a follow-up charge.
- Confirm the visit fee and what it includes before you book.
- Ask which labs or procedures are commonly billed separately for your concern.
- Verify your insurance copay or deductible status for a problem-oriented visit.
- Request the self-pay rate if you are not using insurance, and confirm what it covers.
- Match the appointment length to the complexity of your concern, and ask the scheduler if you are unsure.
After the visit, review the explanation of benefits or the itemized bill carefully. Compare the visit charge with the allowed amount and your cost sharing. If a separate lab or facility charge appears, check whether it was disclosed or expected. Billing errors are not rare, and a polite call to the billing office can resolve many of them. Keeping notes from your booking conversation, including any quoted self-pay rate, makes that call easier.
Finally, remember that the cost of a 15 minute primary care appointment is only one part of the value calculation. A short visit that answers your question and avoids a return trip is a good use of money. A short visit that leaves you with more questions and a follow-up bill is not, even if the initial fee looked low. The best approach is to treat the visit fee as a starting price, ask what else is likely to be billed, and choose an appointment length that fits the problem you are bringing to the clinician.
For readers who want to understand the telehealth side of primary care, including which medications clinicians commonly discuss and which safety points always come up, the educational guides at DoctorsHome are a useful next stop. They do not diagnose, prescribe, or book visits, but they can help you walk into a short appointment with better questions and a clearer sense of what the visit can and cannot cover.